Readers probably caught the headline last week: the U.S. national debt officially crossed the $40 trillion mark. If it feels like you’ve lost track of how big the number has gotten, you’re not alone.
The fact that total federal debt crossed $40 trillion is symbolically important. And it’s true the federal government continues running large deficits during an economic expansion, which has arguably contributed to rising long-term Treasury yields. These are all issues to keep on our radar.
But I also think investors should be careful about focusing only on the $40 trillion headline number and framing it in their minds as a debt problem where the danger to markets and the economy is imminent. Large numbers can create alarm, but they do not always tell us whether a debt burden is becoming immediately unmanageable.
In my view, the better way to analyze federal debt is to focus on debt-service capacity. In plain English, this means asking how much of the government’s revenue is needed just to pay interest on the debt.
This metric matters because interest expense competes with other priorities. Every dollar used for interest is a dollar that cannot be used as easily for defense, infrastructure, healthcare, entitlement programs, tax relief, or future investment. As it stands today, the issue is not whether the U.S. can make its next interest payment—it’s whether rising interest costs gradually reduce the government’s ability to stimulate the economy in other ways.
Interest costs as a share of federal tax receipts have risen meaningfully in recent years, which is a real concern. But they remain below the peaks reached in the 1980s and early 1990s, when interest rates and fiscal concerns were also elevated. Federal tax receipts also still exceed interest payments by a wide margin (chart below), which is one reason markets are not treating U.S. debt as a near-term solvency issue.
Federal tax receipts (blue line) vs. Federal interest payments (green line)
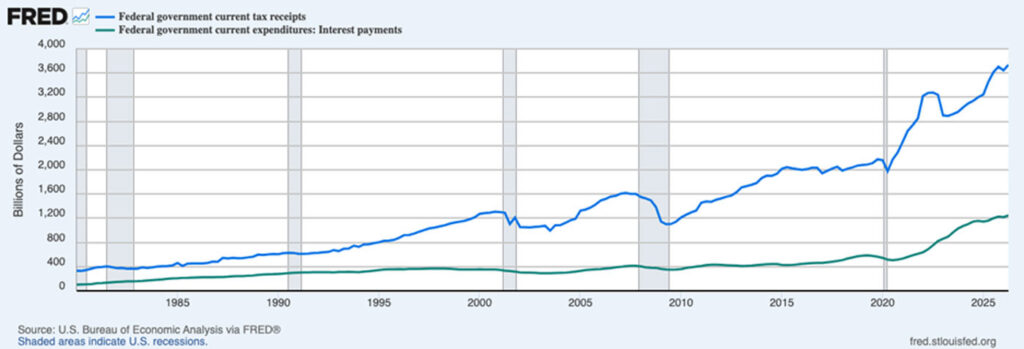
Source: Federal Reserve Bank of St. Louis1
I think it’s fair to say, however, that the margin for error is narrowing. Put simply, the U.S. should not run large deficits indefinitely and assume the bond market will absorb every new dollar of debt at whatever yield policymakers prefer. The bond market has recently been reminding investors of this latter point.
If the $40 trillion milestone matters, this is why. It is not about imminent crisis—it’s about higher debt and higher rates leaving less room for error, and making sustained economic growth increasingly important.
The U.S. has carried high debt burdens before, most notably after World War II. What helped reduce that burden over time was not simply austerity or aggressive debt repayment. It was growth, productivity, inflation, and time. A growing economy makes a large debt burden easier to manage, while a slowing economy makes it harder.
For now, the U.S. continues to see economic growth, resilient corporate earnings, and strong demand for Treasury securities. Those conditions do not erase the debt problem, but they do help explain why markets are not treating $40 trillion as a breaking point.
The risk is that this balance becomes harder to maintain over time. If interest costs keep rising faster than tax receipts, policymakers may face tougher trade-offs around spending, taxes, and future investment. That is the part of the story investors should watch most closely. Not necessarily the headline debt number by itself, but whether the economy remains strong enough to carry the burden.
Bottom Line for Investors
The U.S. crossing $40 trillion in debt is a serious milestone, and investors are right to pay attention. But the better focal point, in my view, is whether the U.S. can continue servicing its debt while maintaining enough flexibility to support growth and respond to future challenges.
For now, the evidence still points to a long-term sustainability issue, not a near-term solvency crisis.
1 FRED, Federal Reserve Bank of St. Louis. Federal Government Current Tax Receipts and Federal Government Current Expenditures: Interest Payments.
DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.
Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.
This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.
Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.
The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.
The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.
The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.
Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.
Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.