
All Posts By

BayTrust Financial

Mitch Zacks – Weekly Market Commentary: Why This Rate Hike Probably Won’t Be the Last

By Weekly Market Commentary

When Federal Reserve Chairman Kevin Warsh was appointed, much of the market concern centered around whether he would push too hard for monetary easing—at a time when inflation was above target and the economy was growing steadily.

What a difference a few months of hot inflation can make.

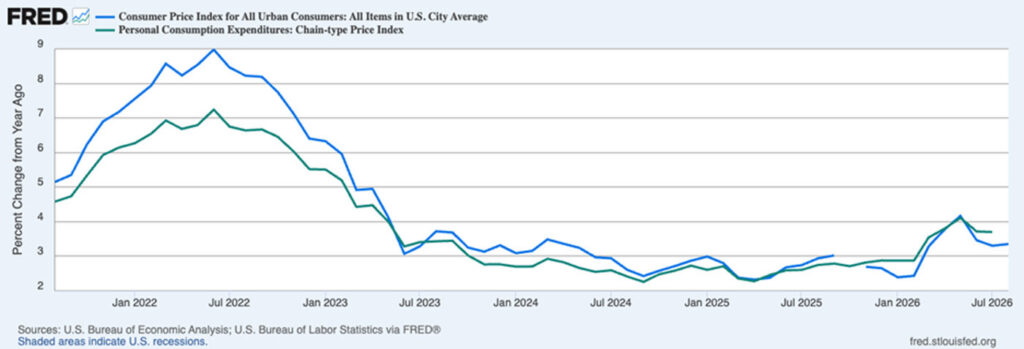
August CPI showed prices rising 0.4% month-over-month and 3.4% year-over-year, and the Fed’s own September projections now put 2026 PCE inflation at 3.7% and core PCE inflation at 3.4%, both well above its 2% target.1

CPI (blue line) and the PCE Price Index (Green Line) Have Been Pressured Higher in 2026
Source: Federal Reserve Bank of St. Louis2

I want to be fair in making the point that the numbers do not suggest inflation is spiraling out of control, especially given the outsized impact of higher energy prices. But we’re certainly seeing an end to the downward trajectory that started in the summer of 2022, with recent price pressures being enough to motivate all 12 of the Fed’s voting members to push rates higher.

History tells us we should expect more hikes from here.

Federal Reserve rate changes tend to be serially correlated, meaning policy moves often come in sequences rather than isolated steps. Looking at actual changes in the federal funds target since 2003, there have been 60 rate changes. On the 59 occasions when one change was eventually followed by another, 52 of them—or roughly 88%—moved in the same direction as the prior change.3 In other words, a hike is almost always followed by another hike, with the same going for cuts.

The individual cycles make the pattern easier to see. The Fed raised rates 17 consecutive times from 2004 through 2006. It then delivered 11 hikes across 2022 and 2023. More recently, the Fed cut rates six consecutive times across 2024 and 2025 before reversing direction last week. This serial correlation is sometimes referred to as “interest-rate smoothing,” with central banks generally preferring to adjust policy incrementally as they receive new information about inflation and growth—rather than making one large move and immediately reversing course.

The Fed’s own projections point in the same direction today. Following this week’s increase, the median policymaker projection puts the federal funds rate at 4.1% at year-end, compared with the current midpoint of 3.875%. 16 of 18 policymakers expect at least one additional increase before year-end.

For investors, the big picture shows us a world where financial conditions are gradually being tightened. The European Central Bank and Bank of Japan have recently raised rates, while the Bank of England has adopted a more hawkish posture as energy prices and inflation remain elevated. It looks to me like a renewed global tightening cycle, which I think could have implications for equity market volatility (as I wrote about recently).

It’s a trend worth watching closely, though I expect this tightening cycle to be far less aggressive than what investors experienced in 2022 and 2023. In other words, not enough to derail the bull market. The larger questions remain whether inflation continues to moderate, whether economic and earnings growth hold up, and whether tighter policy eventually begins to materially weaken demand. When I zoom out and take it all into consideration, I don’t think two or three quarter-point hikes are meaningful enough to materially change the earnings or economic backdrop on their own.

Bottom Line for Investors

This week’s quarter-point rate hike was widely expected, and I do not think investors should overhaul portfolios because the federal funds rate moved 25 basis points higher. The more interesting signal is the direction of policy. Fed rate changes have historically tended to come in sequences, the central bank’s own projections point to additional tightening, and other major central banks are confronting many of the same inflation pressures. It’s something to watch, but probably not enough to fundamentally alter the investment landscape, in my view.

The final takeaway that I think deserves attention is the idea that pressure could/would compromise Federal Reserve independence. In my view, the rate hike decision provides a useful piece of evidence in the other direction. With midterm elections approaching and the administration openly favoring lower borrowing costs, the Fed still voted unanimously to raise rates in response to inflation. That looks like a central bank responding to economic data, not political pressure. This point becomes even more salient if the Fed decides to raise rates again from here, which I believe will be the case.

1 Federal Reserve. September 16, 2026. Board of Governors of the Federal Reserve System.

2 FRED Fred Economic Data. September 11, 2026. Consumer Price Index for All Urban Consumers: All Items in U.S. City Average

3 Federal Reserve. September 16, 2026. Board of Governors of the Federal Reserve System.

DISCLOSURE

Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties.  Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
Mitch Zacks – Weekly Market Commentary: More Market Volatility May Be Coming—and That’s OK

By Weekly Market Commentary

After a strong second quarter when stocks rebounded sharply from war- and energy-driven volatility, equity and fixed income markets have settled into a more unsettled holding pattern. Selling pressure has appeared in spurts, and the day-to-day trading environment has become noticeably less comfortable.1

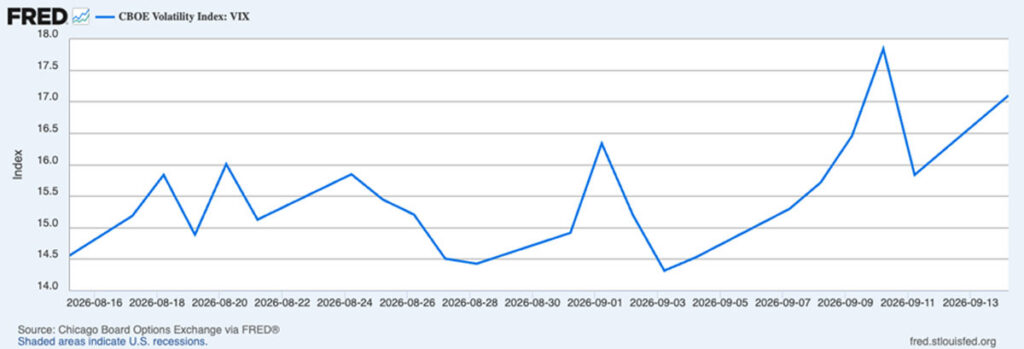
The Volatility Index (VIX) has ticked higher over the past several weeks, as investors seem to be pricing in more uncertainty than they were earlier this summer.2

CBOE Volatility Index: VIX

Source: Federal Reserve Bank of St. Louis3

The rising volatility and selling pressure haven’t emerged out of thin air.

Oil is one obvious source of concern. U.S. crude prices have risen about 20% over the past three weeks to over $100 per barrel, while diesel has climbed to a record $6.23 per gallon and gasoline has rebounded to $4.32 (as I write). At the same time, commercial fuel inventories have been drawing down, and disruptions to Saudi Arabia’s East-West pipeline have reportedly removed another 2.5 million barrels per day of supply from an already tight global market.

We know that some of the buffers that helped absorb the initial energy shock earlier this year have diminished. But even still, $100 oil itself has never been an especially useful market threshold. Between 2008 and the start of 2026, Brent closed above $100 per barrel in over 200 weeks, and equity markets rose in forward 12-month periods over 80% of the time. In other words, the bull market and the economy withstood higher oil much of the time.

In my view, the more important risk today is persistence—whether elevated energy costs last long enough to weaken consumer spending, business activity, and corporate earnings. This risk remains on our radar, but we’re not seeing signs of it yet.

Interest rates are another source of pressure. The 10-year Treasury yield briefly touched 5% this week, after starting the year near 4.15%. That’s a substantial jump, and higher yields can of course increase borrowing costs throughout the economy and place pressure on stock valuations, particularly when rates move quickly.

But here too, the market has shown an ability to absorb the move. The S&P 500 remains up more than 10% this year despite the steady rise in yields. Strong earnings and economic growth can provide support as rates move higher, and we’ve been fortunate to see record-level earnings from Corporate America. Estimates for future quarters keep moving higher as well, which is the reason I think the 10-year at 5% didn’t trigger a major equity market move.

Finally, investors are once again adjusting expectations for Federal Reserve policy. Going into Wednesday’s policy meeting, markets were assigning a roughly 85% probability to a September rate hike, following August’s CPI print of 3.4%. With the Fed raising rates a quarter point, the market got what it expected, but the choppiness leading up to the decision may have been about resetting expectations. As I’ve written many times before, a quarter-point move by itself is unlikely to determine the market’s long-term direction, but rapid changes in Fed expectations can produce meaningful short-term swings.

Taken together, there is plenty here to give markets a reason to remain choppy, which is why I implied in the title that more volatility may be coming.

But here’s why that’s ok.

When markets rise steadily for months, normal volatility starts to feel abnormal. A 2% down day feels ominous. A 5% pullback over a few weeks can attract warnings about what could come next, and a 10% correction can suddenly feel like evidence that the entire investment thesis has changed.

But investors need to remember that volatility serves an important purpose in markets. Prices constantly adjust as investors digest new information, reassess risks, and change their expectations about future earnings. Corrections can temper excessive optimism, reset valuations, and force investors to become more discerning about what they own. In that sense, the occasional pullback is a sign that markets are functioning normally.

Bottom Line for Investors

A meaningful correction at some point would hardly surprise me—and by itself, it would not change my long-term view. Volatility is part of how markets reset expectations, reprice risk, and ultimately create healthier conditions for future gains.

For investors, the more important question is whether anything fundamental has changed in your financial goals, time horizon, or long-term investment thesis. If the answer is no, a period of market turbulence is usually a reason to stay disciplined—not a reason to abandon the plan.

1 Wall Street Journal. September 14, 2026. “Oil Executives Say the Great Fuel Crisis Is Here.”

2 Morningstar. September 14, 2026. “Why the Odds of a US Fed Interest Rate Hike Just Shot Higher.”

3 FRED Fred Economic Data. September 17, 2026. “CBOE Volatility Index: VIX (VIXCLS)”

DISCLOSURE

Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties.  Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.

Mitch Zacks – Weekly Market Commentary: On the Growing Concern Over U.S. Debt

By Weekly Market Commentary

Readers probably caught the headline last week: the U.S. national debt officially crossed the $40 trillion mark. If it feels like you’ve lost track of how big the number has gotten, you’re not alone.

The fact that total federal debt crossed $40 trillion is symbolically important. And it’s true the federal government continues running large deficits during an economic expansion, which has arguably contributed to rising long-term Treasury yields. These are all issues to keep on our radar.

But I also think investors should be careful about focusing only on the $40 trillion headline number and framing it in their minds as a debt problem where the danger to markets and the economy is imminent. Large numbers can create alarm, but they do not always tell us whether a debt burden is becoming immediately unmanageable.

In my view, the better way to analyze federal debt is to focus on debt-service capacity. In plain English, this means asking how much of the government’s revenue is needed just to pay interest on the debt.

This metric matters because interest expense competes with other priorities. Every dollar used for interest is a dollar that cannot be used as easily for defense, infrastructure, healthcare, entitlement programs, tax relief, or future investment. As it stands today, the issue is not whether the U.S. can make its next interest payment—it’s whether rising interest costs gradually reduce the government’s ability to stimulate the economy in other ways.

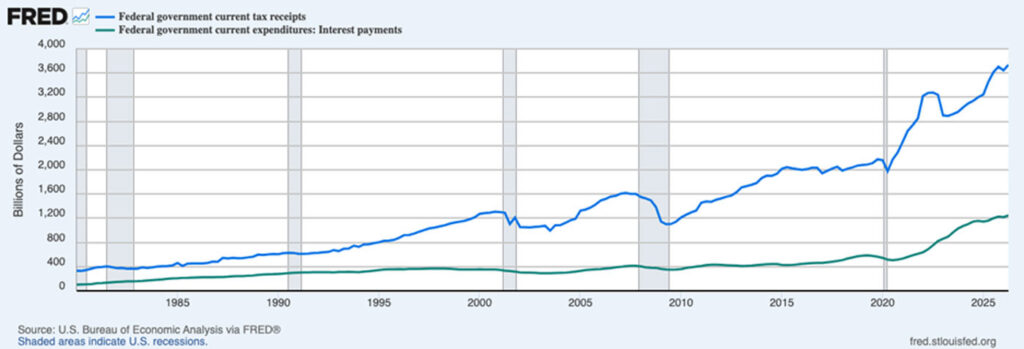
Interest costs as a share of federal tax receipts have risen meaningfully in recent years, which is a real concern. But they remain below the peaks reached in the 1980s and early 1990s, when interest rates and fiscal concerns were also elevated. Federal tax receipts also still exceed interest payments by a wide margin (chart below), which is one reason markets are not treating U.S. debt as a near-term solvency issue.

Federal tax receipts (blue line) vs. Federal interest payments (green line)

Source: Federal Reserve Bank of St. Louis1

I think it’s fair to say, however, that the margin for error is narrowing. Put simply, the U.S. should not run large deficits indefinitely and assume the bond market will absorb every new dollar of debt at whatever yield policymakers prefer. The bond market has recently been reminding investors of this latter point.

If the $40 trillion milestone matters, this is why. It is not about imminent crisis—it’s about higher debt and higher rates leaving less room for error, and making sustained economic growth increasingly important.

The U.S. has carried high debt burdens before, most notably after World War II. What helped reduce that burden over time was not simply austerity or aggressive debt repayment. It was growth, productivity, inflation, and time. A growing economy makes a large debt burden easier to manage, while a slowing economy makes it harder.

For now, the U.S. continues to see economic growth, resilient corporate earnings, and strong demand for Treasury securities. Those conditions do not erase the debt problem, but they do help explain why markets are not treating $40 trillion as a breaking point.

The risk is that this balance becomes harder to maintain over time. If interest costs keep rising faster than tax receipts, policymakers may face tougher trade-offs around spending, taxes, and future investment. That is the part of the story investors should watch most closely. Not necessarily the headline debt number by itself, but whether the economy remains strong enough to carry the burden.

Bottom Line for Investors

The U.S. crossing $40 trillion in debt is a serious milestone, and investors are right to pay attention. But the better focal point, in my view, is whether the U.S. can continue servicing its debt while maintaining enough flexibility to support growth and respond to future challenges.

For now, the evidence still points to a long-term sustainability issue, not a near-term solvency crisis.

1 FRED, Federal Reserve Bank of St. Louis. Federal Government Current Tax Receipts and Federal Government Current Expenditures: Interest Payments.

DISCLOSURE

Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties.  Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.

Mitch Zacks – Weekly Market Commentary: Why Equity Investors Are Actively Rotating Capital

By Weekly Market Commentary

A diversified portfolio of U.S. stocks has performed well over the past few years, but the ability to generate strong alpha has largely relied on being overweight by a few key names (most of which are in the “Magnificent Seven”).1

But this has not been the case in 2026.

As I write, the S&P 500 Equal Weight Index is outperforming the market-cap weighted S&P 500 Index by approximately 200 basis points year-to-date, which sends a clear signal that investors have been rotating capital away from the hottest trade.

We know this because the traditional S&P 500 is market-cap weighted, which means the largest companies (mega-cap tech stocks) have the greatest influence on performance. The equal-weight version gives every company the same weight. When the equal-weight index outperforms, it suggests the average stock is doing better than the headline index may indicate.

Put simply, many of “the other 493 stocks” in the index are quietly experiencing solid, sometimes bigger gains. This is a healthy development, and I think the reason comes down to three forces: earnings strength, fading uncertainty, and more selectivity within the AI trade.

Let’s start with earnings.

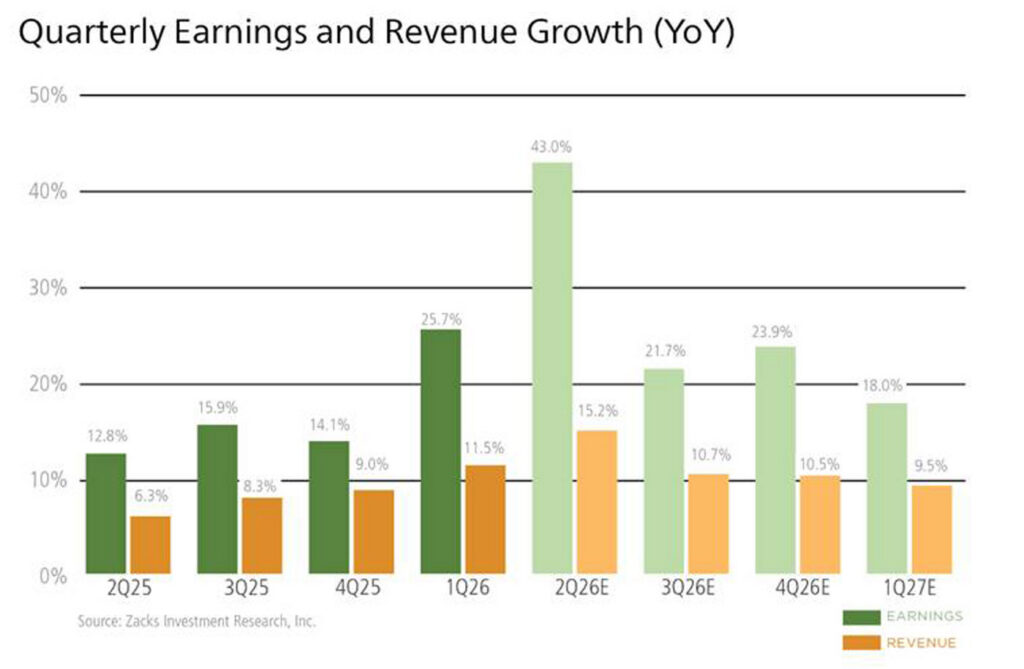
According to our colleagues at Zacks Investment Research, aggregate earnings for the S&P 500 grew +40.9% year-over-year on +14.5% higher revenues. Positive surprises were also widespread, with 83.8% beating EPS estimates and 76.9% topping revenue estimates.

To be fair, some of the headline earnings strength is still being driven by a few very large companies. But the earnings story does not disappear when those companies are removed. As seen on the nearby chart, if we exclude Technology sector earnings and a few key earnings drivers in Q2, we still get around 15% year-over-year earnings growth—a strong improvement from previous years.

Zacks2

The same point shows up within the Technology sector. Zacks data shows that Q2 earnings growth in the Tech sector remains heavily concentrated in Nvidia, Micron, and Alphabet. Stripping out those three companies reduces Q2 earnings growth for the rest of the Tech sector from +95.2% to +33.7%. Quite a revision, but still very strong overall.

The second force, I think, is driving the broadening is fading uncertainty. Market leadership often narrows when uncertainty is high, as investors tend to crowd into the companies and themes with the clearest earnings visibility, strongest balance sheets, or most durable growth. Over the last few years, that has clearly been mega-cap Technology and AI-linked stocks.

But in 2026, several major risks have become easier for markets to process. The war and oil price volatility are of course still front-and-center, but investors have had six months to gauge the impact on energy prices and corporate earnings. Similarly, tariff policy has returned to headlines, but the market has moved beyond the initial shock phase and is now assessing company-by-company exposure. The Fed’s outlook on interest rates may be the remaining wild card, but I think if we’re talking about 25 basis points in either direction, it’s not enough to factor as a negative surprise.

The final force is more selectivity within the AI trade. In July, AI-linked areas like semiconductors, memory, power, liquid cooling, and optical networking all came under pressure. When a trade becomes more volatile, investors often look for ways to reduce concentration and find opportunities elsewhere. And indeed, in August, the rebound became more differentiated, with investors rewarding some parts of the AI ecosystem more than others. That type of selectivity is healthier than simply buying the entire theme indiscriminately.

It has also meant investors are increasingly looking for earnings growth in sectors that were written off earlier in the year—which is how rotation often works. Companies and sectors that were overlooked earlier in the year are getting a second look as fundamentals improve and the macro backdrop becomes easier to assess. In my view, that is an important shift. A rally led by a handful of mega-cap stocks can work for a while, but a rally supported by more companies, more sectors, and more earnings drivers tends to be a healthier market environment.

Bottom Line for Investors

The U.S. stock market has not completely moved past the concentration issue. But the rally is becoming broader, as equal-weight outperformance, strong earnings growth outside a few headline names, and more participation across sectors all suggest the market has more support beneath the surface than many investors may realize.

For diversified investors, that is an encouraging signal. Diversification does not always feel valuable when leadership is narrow, but it becomes important when leadership changes—which is what we’ve seen in 2026 year-to-date.

1 Zacks. August 19, 2026. https://advisor.zacksim.com/e/376582/ergy-fuel-sp-500-growth-engine/5vtn75/1602110950/h/5YE_Y8p4MEGevotlIHe7ekn8jgFyHzIO9HRgP0zmzCM
2 Zacks. August 19, 2026. https://advisor.zacksim.com/e/376582/ergy-fuel-sp-500-growth-engine/5vtn75/1602110950/h/5YE_Y8p4MEGevotlIHe7ekn8jgFyHzIO9HRgP0zmzCM

DISCLOSURE

Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties.  Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
Mitch Zacks – Weekly Market Commentary: The Bond Market Is Sending a Message

By Weekly Market Commentary

Bond yields have moved higher in recent weeks, which has prompted a debate among market participants as to the potential cause: rising inflation expectations, market consternation at rising deficits in the U.S. and abroad, sinking global demand for Treasurys, or some combination of forces.1

10- and 30-Year U.S. Treasury Bond Yields, Year-to-Date

Source: Federal Reserve Bank of St. Louis2

Then, a surprise announcement last week by Treasury Secretary Scott Bessent sent the debate into overdrive.

Secretary Bessent announced plans to expand long-dated U.S. Treasury bond buybacks, with the U.S. Department of the Treasury at least doubling the size of certain buyback operations from $2 billion to $4 billion. The buybacks would focus on the long end of the curve—meaning 10- and 30-year U.S. Treasurys—with the move framed as an effort to support market functioning and liquidity.

But there seemed to be one glaring problem—there was no noticeable issue with liquidity or the ‘plumbing’ of Treasury markets. Treasury auctions were still clearing, dealers were not visibly pulling back, and the market was not facing the kind of forced selling we saw in March 2020. Markets took the news skeptically, and yields ultimately ticked higher—not lower.

I won’t go too deep into the weeds here, but the signal taken from markets was that the Department of the Treasury was intervening in bond markets not because of liquidity issues, but because of pricing issues. In other words, the actual goal was to put a support under bond prices, which equates to an effort to push yields lower, arguably in support of keeping borrowing rates low and financial conditions accommodative.

This was the story that was playing out in headlines last week, but I think it all lacked important context. A $4 billion buyback operation sounds large in isolation, especially after headlines emphasized that Treasury was “doubling” the size of certain operations. But scale is important here, as Treasury cash securities trade around $1 trillion per day in a roughly $32.2 trillion Treasury market. In that context, a $2 billion buyback increase is unlikely to materially change the market’s supply-demand balance on its own.

Rising long-term rates are usually framed as a negative, because they can raise borrowing costs, push mortgage rates higher, and weigh on stock valuations. All these outcomes are real and possible, but rising yields can also serve as an important market signal. When investors demand more compensation to lend for 10, 20, or 30 years, they may be sending a message about inflation, Treasury supply, fiscal policy, or uncertainty. In this sense, markets can ‘demand’ a certain discipline to push policymakers into difficult choices.

There is also a constructive side of the yield story that often gets overlooked.

First, higher yields mean investors are being paid more to own bonds over time. This yield compensation can come with price volatility, but it does improve the overall income profile of high-quality fixed income for long-term investors.

Second, a steeper yield, where long duration bonds see more upward pressure than the short end of the curve, can improve the economics of bank lending. Banks generally fund themselves at shorter-term rates and lend at longer-term rates. When long-term rates rise relative to short-term rates, lending can become more profitable. In the current context, loans and leases in bank credit for all commercial banks were up 7.3% year-over-year as of mid-August, arguably aided in part by rising long duration yields.

Ultimately, higher yields are not automatically positive or negative, but they do carry important information. If yields are rising because growth remains resilient, the economy and corporate earnings may be able to absorb some of the pressure. If yields are rising because inflation expectations or fiscal concerns are worsening, investors should take that signal seriously. For now, I don’t think the recent moves have been sharp enough to suggest a bond market in crisis. But they have been meaningful enough to remind investors that long-term rates, federal borrowing needs, and inflation expectations all deserve close attention.

Bottom Line for Investors

Rising long-term yields deserve attention, but they do not automatically point to a bond market crisis. They are a signal—about inflation, growth, Treasury supply, deficits, and the return investors require to lend money for longer periods.

The right response is not to react emotionally to every move in rates. It is to listen to what the bond market is saying, while keeping the message in perspective.

1 Wall Street Journal. August 21, 2026. https://advisor.zacksim.com/e/376582/mod-Searchresults-pos-5-page-1/5vsxd2/1594610707/h/tepFt_XVIUI0L2XHtmh5Z38sxYUoDnbS3usl92cRACE

2 Fred Economic Data. August 26, 2026. https://advisor.zacksim.com/e/376582/series-DGS10/5vsxd5/1594610707/h/tepFt_XVIUI0L2XHtmh5Z38sxYUoDnbS3usl92cRACE

DISCLOSURE

Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties.  Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
Mitch Zacks – Weekly Market Commentary: The Next “AI Concentration” Story May Be in the Bond Market

By Weekly Market Commentary

For years, investors have been warned about mega-cap tech concentration in the stock market. Readers have seen the statistics before—the “Magnificent Seven” stocks account for 30+% of the S&P 500 index, corporate earnings results are being pulled higher by a few key hyper-scalers, etc.1

But there is another concentration story developing in the capital markets that has received far less attention: the impact AI is having on credit markets.

In the early days of the AI investment frenzy, infrastructure was being funded primarily through free cash flow and equity markets. But as I take stock of the environment today, it’s clear that an increasing share of investment is coming from debt. Hyper-scalers and the broader AI ecosystem are issuing bonds to help finance data centers, chips, power infrastructure, cloud capacity, and other long-term investments tied to artificial intelligence.

The share of new investment-grade debt tied to AI has climbed quickly:

  • 2024: roughly 1% of year-to-date supply
  • 2025: roughly 7% of year-to-date supply
  • 2026: roughly 18% of year-to-date supply

Hyper-scalers issued roughly $108 billion of debt globally in 2025. So far in 2026, that figure has reached about $194 billion. Across the broader AI ecosystem, total AI-related debt issuance is estimated at nearly $500 billion year-to-date, with hyper-scalers accounting for about 40% of that total. In my view, this is starting to look like the credit-market parallel to what many investors already understand about equities.

In other words, this is not just a handful of large technology companies borrowing money. It is part of a much broader credit cycle tied to the AI buildout.

I want to pause here to make it clear that I do not think there is a leverage problem in the markets today. Many of the largest issuers remain highly rated, cash-generative, and in strong financial condition. The technology sector broadly entered this cycle with strong balance sheets and relatively low leverage, which gives many companies room to borrow for strategic investment. In many cases, AI-related borrowing is being used to build productive assets that companies believe will support future growth.​​​​

The trillion-dollar question, however, is: will the payout on AI be as high as the optimistic forecasts say it will be? Uncertainty about the answer will eventually place limits on investor demand for new debt.

For now, at least, there is no obvious sign that broad investment-grade credit markets are under major stress. Credit spreads have moved somewhat, but they remain low relative to periods of real market strain. Borrowers still have access to capital, and investor demand remains present.

Looking ahead, though, a multi-year wave of issuance can change the shape of a market. It can influence spreads, duration exposure, issuer concentration, and the terms investors require to absorb new supply. It can also pull in new structures—private credit, infrastructure funds, real estate lenders, and others. When a hot investment theme attracts large pools of capital, the risk is that lenders begin stretching terms, accepting weaker protections, or underestimating how difficult it may be to exit if conditions change.

As more AI financing moves into leases, project finance, infrastructure lending, and private credit structures, investors may have a harder time judging how much risk is building and where it ultimately sits. I’ve written before about cracks showing up in private credit markets, so this will be a story to continue watching.

The same principle applies to fixed income more broadly. Bonds are often discussed as if they are one asset class, but there are major differences between Treasurys, municipal bonds, investment-grade corporates, high-yield bonds, private credit, and structured finance. Each has a different role in a portfolio, and each carries different risks.

For investors, the AI credit story is another reminder that diversification matters in fixed income too. A portfolio can benefit from exposure to high-quality corporate bonds, but that does not mean investors should ignore issuer concentration, duration, credit quality, or the purpose of the borrowing. Investment-grade corporates can add income, but they still require careful credit selection.​​​​​​

Bottom Line for Investors

The AI credit story I’m telling here is not a warning that the largest technology companies are suddenly overleveraged. Most still have strong earnings, solid balance sheets, and ample access to capital. The bigger issue for investors, in my view, is exposure. The same AI theme that has created concentration concerns in equity markets is now showing up in credit markets, through bond issuance, data-center financing, lease commitments, and private-market structures that may be harder for investors to fully see.

The takeaway is that fixed income should not be treated as a passive endeavor for yield. It requires active oversight, credit discipline, and diversification across Treasurys, municipals, and high-quality corporates.

1 Goldman Sachs. 2026.

DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties.  Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
Mitch Zacks – Weekly Market Commentary: Is This Market Too Hot? The Data Says No.

By Weekly Market Commentary

Many investors are looking at the current market rally and wondering if it is sustainable. If you’re a retiree, the concern may run even deeper, as your natural focus is on preserving gains, avoiding major drawdowns, and making sure your portfolio can support long-term income needs.

To put it another way: when stocks move higher in a hurry, it is reasonable to ask whether the market has moved too far, too fast.

The only real way to answer the question is to look at the earnings and economic fundamentals, in my view. Market volatility, which I often remind readers can move stocks in both directions, is driven by sentiment in the short run, but over time, earnings, economic growth, business investment, and consumer demand matter far more. If that’s the criteria we use to evaluate the current market, the rally looks to me like it has fundamental support.

The clearest tailwind is coming from corporate earnings.

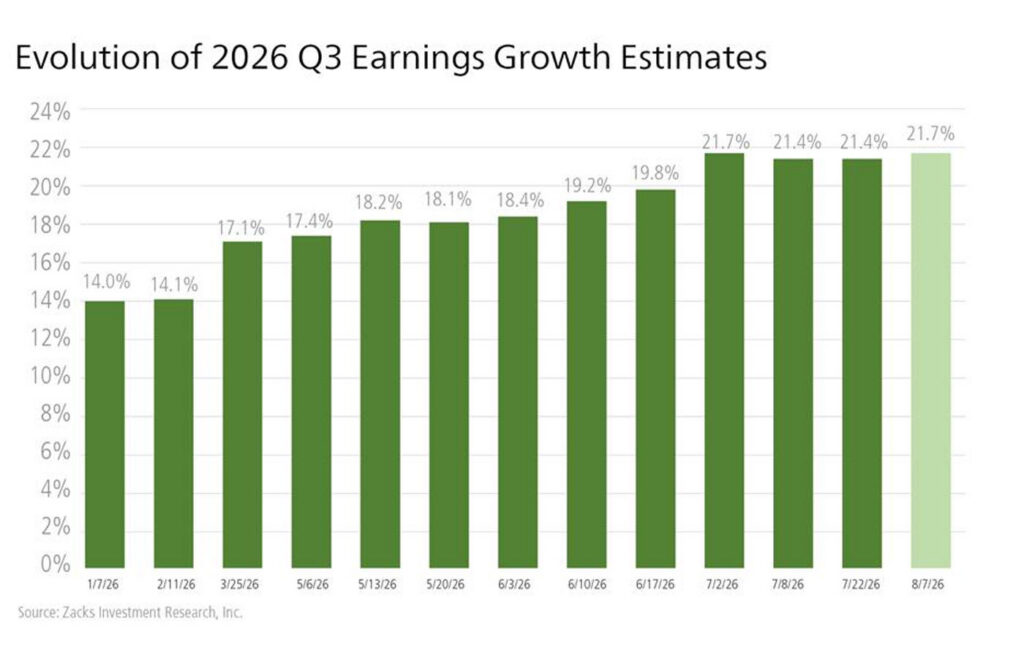
Through August 7, 444 S&P 500 companies had reported Q2 results, representing nearly 89% of the index’s membership. For those companies, earnings were up 42.2% from the same period last year on 14.8% higher revenues. That’s not a misprint—42.2% year-over-year earnings growth! The beat rates were also strong, with 82.7% of companies exceeding earnings estimates and 76.4% topping revenue expectations.

Zacks1

To be fair, the headline earnings growth rate is getting a major boost from a few large companies. Alphabet’s Q2 results included a sizable non-operating unrealized gain tied to its SpaceX stake, and companies like Nvidia and Micron continue to have an outsized impact on the Technology sector’s growth rate. But the broader earnings picture still looks constructive even after accounting for that concentration. According to our colleagues at Zacks Investment Research, total S&P 500 earnings are expected to rise 27.1% in 2026. Excluding the Technology sector, earnings are still expected to increase 14.6%—a solid showing that I think speaks to broad economic strength.

The U.S. GDP data tells a similar story. Headline Q2 real GDP growth slowed to 1.5% annualized from 2.1% in Q1, which may seem fairly “muddle-through” for an economic growth rate. But underneath the headline figure, private-sector components were stronger than many appreciate, and I tend to think these data matter more than government spending and imports/exports, for instance.

The private sector components—consumer spending, business investment, and residential investment—grew at a 3.3% annualized pace, the strongest reading in more than three years. Personal consumption expenditures rose 3.2% annualized after increasing just 0.5% in Q1, and durable goods spending climbed 6.8%. Business investment also remained strong, with capital spending up 8.4% annualized after a 10.6% gain in Q1. These are strong prints across the board.

It’s not all big growth and expansion, however. July payrolls fell by -23,000, missing expectations for a gain. But a meaningful part of the July decline appears to have come from local government employment, while private employers still added 30,000 jobs. That is soft, to be sure, but it is not the same as broad labor market deterioration. Monthly jobs data can also be choppy and subject to revision, so the key is whether weakness persists. It’s something to watch in the months ahead.

Bottom Line for Investors

Strong rallies can make investors nervous, especially when they happen quickly and when leadership appears concentrated in a handful of large companies. But I’d argue the current market advance has not been built on sentiment alone.

The data are giving investors a reasonable explanation for the market’s strength. Corporate earnings are growing, revenues are rising, business investment remains healthy, and the economy continues to expand. Earnings expectations continue to move higher, too, which speaks to the corporate outlook.

The AI buildout may be difficult to fully grasp, but it is showing up in real spending, real revenue, and real earnings power. And that’s what matters to stocks.

© Zacks Investment Management  |  Privacy Policy
1 Zacks.com. August 7, 2026. https://advisor.zacksim.com/e/376582/s-validate-market-fundamentals/5vrgvb/1585478856/h/Qf3MCWDl1bjP_ce9YNWQWZyava0xOf9QAQYDzLhlusQ 

DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties.  Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
Mitch Zacks – Weekly Market Commentary: What a Hedge Fund Blowup Says About Tech Volatility

By Weekly Market Commentary

The past few weeks have marked a volatile stretch for technology stocks—in both directions.

In July, several AI-related sub-sectors like semiconductors, memory, chips, and AI infrastructure came under intense selling pressure. The Philadelphia Semiconductor Index, for instance, nearly entered bear market territory in July, with every member of the index trading below its 50-day moving average.

Readers may have also seen stories on SK Hynix, which embodied the scale of the volatility. The company had just completed a blockbuster Nasdaq debut, raising more than $26 billion. But shares plunged -15% in one day even after a record-breaking earnings report, with operating profit up more than 500% year-over-year. The news stories and accompanying sharp moves in select stocks were head-spinning.1 

Investors were also concerned with Google’s Q2 earnings, which had the company posting its first negative free cash flow period since becoming public. Google remains highly profitable and deeply embedded in the AI race, but the market’s reaction showed that investors are paying closer attention to the cost of staying competitive in AI, not just the potential upside.

Which brings me to the Situational Awareness story. For readers who aren’t familiar, Situational Awareness ‘was’ the hedge fund founded by a former OpenAI researcher with no previous investment experience. The fund reportedly grew from hundreds of millions of dollars to a peak of approximately $45 billion in assets in less than two years, helped by a highly concentrated bet on the AI buildout.

The strategy was characterized as “long hardware, short software,” but it was a case study in the perils of becoming over-concentrated in a hot corner of the market and using leverage to juice the bet. In brief, the fund held sizable long positions in companies tied to AI infrastructure, chips, data centers, and power demand, while shorting software companies viewed as vulnerable to AI disruption. It was a concentrated expression of a view many investors have debated: that AI infrastructure would be the biggest near-term beneficiary of the technology wave, while some incumbent software businesses could face pressure.

But in July, both sides of the trade came under pressure at once. AI-infrastructure longs fell sharply, while some software shorts rallied. That meant the portfolio was not hedged in the way investors might expect from a long/short strategy. The long positions lost money, the short positions also lost money, and leverage turned the reversal into a liquidity event.

What happened next was astonishing. Situational Awareness’ assets fell from a peak of roughly $45 billion to about $10 billion in a matter of weeks. Its portfolio value reportedly declined 67% in July, forcing the fund to sell public equity holdings, eliminate leverage, and retain primarily private investments.

It marked a loud, wild cautionary tale about the risks of trying to predict exactly how the AI story will unfold—and using too much leverage and concentration to make that bet.

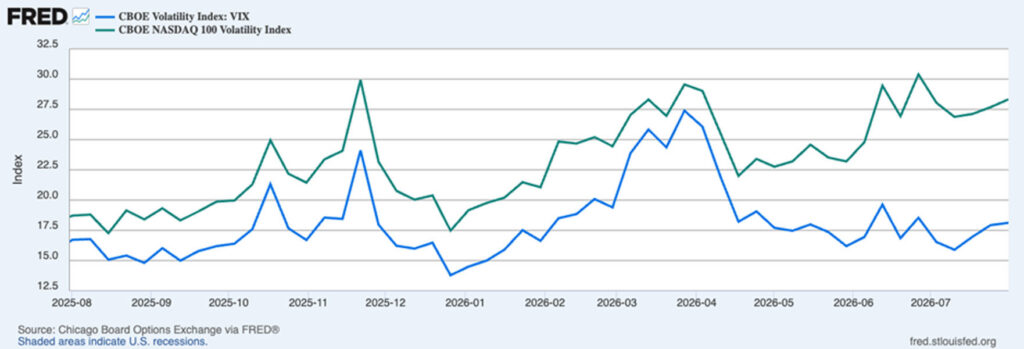
The point I want to make in this week’s column is that the Situational Awareness story—and July’s broader tech volatility—was not just about one fund, one company, or one trade. In fact, investors who were not following the day-to-day action closely may have looked at the broader market and assumed conditions were relatively normal. As the chart below shows, comparing the broad Volatility Index (VIX) to the Nasdaq 100 Volatility Index, broader market volatility was contained while volatility in the Nasdaq 100 was running much hotter.

Source: Federal Reserve Bank of St. Louis2

This is where diversification shows its value. Short-term noise can feel overwhelming when investors are concentrated in the part of the market generating the most headlines. But in a broader portfolio, those moves are only one part of the picture. In July, the S&P 500 was roughly flat, while sectors like Energy and Financials posted solid gains. Capital was rotating, not disappearing.

Diversification is not just about reducing exposure to volatility. It is about maintaining exposure to different sources of return when leadership shifts, so that portfolio returns can smooth out over time. Investors do not need every position, sector, or theme to generate blowout returns to make progress toward their long-term goals.

Bottom Line for Investors

The recent volatility in Tech does not negate the long-term opportunity in AI, semiconductors, software, or innovation more broadly. But it does show how difficult it can be to predict which part of a powerful theme will lead next, and it should remind investors how quickly leadership can shift.

For most investors, the goal is not to capture every upside move in the hottest corner of the market. It is to participate in long-term growth while managing the risk of being too dependent on one theme, one trade, or one moment in time. That is where diversification remains so valuable.

References to individual companies are for illustrative purposes only and should not be interpreted as recommendations to buy, sell, or hold any security.

1Wall Street Journal. July 31, 2026. https://advisor.zacksim.com/e/376582/eness-hedge-fund-imploded-html/5vqmlk/1581299065/h/ILfcWPfeQmsBoYmEmVDhR_dz6nqcAz8KMASdt_zb_YU

2 Fred Economic Data. August 5, 2026. https://advisor.zacksim.com/e/376582/series-VIXCLS/5vqmln/1581299065/h/ILfcWPfeQmsBoYmEmVDhR_dz6nqcAz8KMASdt_zb_YU

DISCLOSURE

Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
Mitch Zacks – Weekly Market Commentary: Why New Tariffs and War May Not Have Much Market Impact

By Weekly Market Commentary

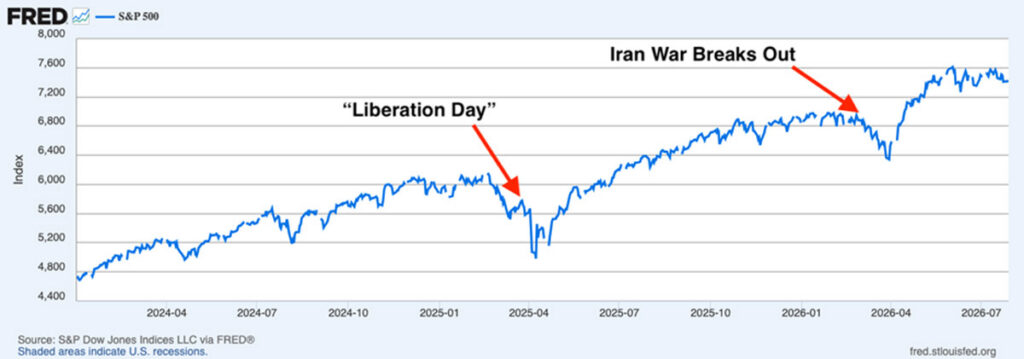
On April 2, 2025 (“Liberation Day”), the Trump administration announced sweeping, ‘reciprocal’ tariffs, and readers likely recall that the initial market reaction was swift and negative. Investors immediately tried to price in worst-case scenarios like higher import costs, pressure on profit margins, slower growth, renewed inflation, and a more complicated path for interest rates.

The conflict involving Iran followed a similar pattern. The initial reaction was sharp, with the S&P 500 nearly reaching correction territory in March. In that instance, investors were pricing-in fears about energy supply, inflation, and higher interest rates.

In both cases, the short-term market reaction was driven by uncertainty, understandably. But we now know that the longer-term response was driven by fundamentals, which remained strong despite these pressures. The S&P 500 rose nearly 18% in 2025 and gained another 10% in the first half of 2026.

The S&P 500 Absorbed Tariff and War Shocks Quickly, Then Continued to Rise (2024 – Present)

Source: Federal Reserve Bank of St. Louis 1

As we enter the second half of 2026, the tariff and war risks are back on the table, with one difference: the market has already spent the past year pricing, testing, and reassessing both risks in real time.

On the tariff side, we’ve seen an additional 50% tariff on a range of Canadian goods, including wine, alcoholic beverages, hockey sticks, cement, and other products. This comes on top of a broader tariff stack that includes duties on Chinese goods, non-USMCA Mexican products, European Union goods, semiconductors, and a proposed tariff (10% – 12.5%) tied to forced-labor concerns across dozens of countries.

I continue to believe that tariffs are not positive for the economy, as they raise costs, create uncertainty for businesses, and can pressure margins for companies with global supply chains or limited pricing power. But they are also no longer a brand-new shock.

When tariffs were first announced in 2025, investors had to consider a wide range of unknowns. Would companies pass the cost on to consumers? Would inflation reaccelerate? Would profit margins compress? Would trade partners retaliate in a way that disrupted global growth?

Investors now know the answers to most of those questions, with the bottom line being that corporate earnings proved more resilient than many feared. The result was not painless, but it also was not the market-breaking event many feared when the policy was first announced.

The renewed conflict involving Iran is similar. It remains a near-term risk because of its potential effects on energy supply, inflation, and interest rates. Earlier this year, investors entered the quarter with oil prices sharply higher and uncertainty surrounding transit through the Strait of Hormuz. But as the quarter progressed, the most severe market assumptions receded. Brent crude fell nearly 40% from its April peak, and oil exports from the Persian Gulf recovered to approximately 60% of their pre-war level.

With the conflict back on, Brent crude is near $90 per barrel, and Gulf transit has become volatile again, with some July days seeing only a fraction of normal vessel traffic through the Strait of Hormuz. While this is not a risk investors should dismiss, the market has seen this pattern before: escalation pushes oil prices higher, inflation expectations rise, bond yields tick higher, and investors reduce expectations for monetary easing. But when energy flows stabilize, much of that pricing can reverse quickly.

The potential consequences of renewed conflict are serious, but the channels through which it affects the economy are increasingly well understood. The same is true for tariffs. Both can still create volatility, but they likely need to worsen, broaden, or surprise markets in a new way to create lasting damage. And I don’t see that happening here.

Bottom Line for Investors

Tariffs and war are not good news, and neither should be ignored. Both can affect prices, margins, interest rates, energy markets, and investor confidence.

But these are no longer entirely new risks. Investors have already seen both issues play out in real time, and the worst-case, long-term market assumptions did not materialize. Volatility remains a distinct possibility, sure. But in my view, unless tariffs or the Iran conflict produce a new and more damaging economic surprise, the more important drivers for investors are still likely to be economic and corporate earnings fundamentals—both of which remain strong.

1 Fred Economic Data. July 28, 2026. https://advisor.zacksim.com/e/376582/series-SP500/5vpynx/1578235974/h/5Zltz33BeMCqHvx_Ik1Tyq9iDVVxJDUEvueQEc0_ENs

DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

​The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.

The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security’s U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.

The PHLX Semiconductor Sector Index is designed to track the performance of a set of companies engaged in the design, distribution, manufacture, and sale of semiconductors. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
 

Copyright © 2026. All rights reserved.

Mitch Zacks – Weekly Market Commentary: With Households Feeling Pressure, why is the Stock Market Booming?

By Weekly Market Commentary

According to the widely watched University of Michigan Consumer Sentiment Index, Americans are not feeling good about the economy. The index fell to 44.8 in May, down from 49.8 in April, marking the lowest reading in the survey’s history dating back to 1952. That means consumer attitudes are now weaker than they were during the 2008 financial crisis, the pandemic recession, the inflation surge of 2022, and the recessions of the 1970s.1

And yet the stock market is trading near all-time highs, having rallied off the lows at the start of the Iran conflict. For many investors, it can be puzzling to understand how a disconnect so large can exist.2

The answer, in my view, is simple and has been consistent throughout history: how consumers feel is not always the same as what consumers do.

Even as consumers report having negative feelings about the economy and financial situations, spending has remained quite firm. Retail sales rose 0.5% in April to $757.1 billion—in line with expectations—and following a stronger 1.6% gain in March. Some of the March increase was tied to higher gasoline prices, and there were signs of cooling in categories like furniture, where sales fell 2% in April after rising 2.6% in March. The detailed read on the data does not suggest consumers are retrenching. It suggests they are becoming more selective.

There’s also the matter of the “K-shaped economy” readers may hear about a lot in the news. The premise is that higher-income households continue spending at a healthy pace, supported by wages, asset values, and stronger balance sheets, while lowerincome households are under more pressure from higher prices.

Data from the New York Fed helps illustrate the split. Since early 2023, real retail spending among households earning more than $125,000 has risen about 7.6%, compared with roughly 3% for middle-income households and just over 1% for lowerincome households. That is a meaningful gap, and it explains why some retailers and service providers continue reporting strong demand while others see consumers becoming more cautious. Even still, however, we’re observing that consumers at all income levels are not pulling back entirely. They are trading down, choosing cheaper brands, prioritizing essentials, and looking for value.

The “K-shaped” argument has some merit, but I think its actual impact can be overstated at times. Higher-income households have always represented a large share of total spending, and lower-income consumers have not disappeared from the economy. The story is less about two completely separate economies and more about different degrees of pressure.

As for consumer sentiment surveys, it’s important for investors to remember that these indicators often reflect what households have already experienced, which in this case involves higher prices from 2022-2023, market volatility, political uncertainty, and more recently, gas price spikes. Markets, by contrast, tend to focus on whether economic reality is better or worse than expectations. When expectations are very low, as they are now, the bar for a positive surprise is also very low. It’s an easy hurdle for markets to overcome.

Not only is consumer spending holding up better than the sentiment surveys suggest, we’re also seeing solid business investment activity and of course, near-record earnings growth.

With nearly all S&P 500 companies reporting first-quarter results as I write, about 83% have beaten earnings expectations, which is the highest beat rate since 2021. Earnings strength has also broadened beyond the AI-related technology complex, with Energy, Materials, Industrials, Communication Services, and Consumer Discretionary companies contributing to better-than-expected results. In this context, negative consumer sentiment may actually be a key component of the constructive setup for markets. It’s part of the wall of worry markets love to climb.

Bottom Line for Investors

To be fair, the U.S. consumer is under pressure, especially from high prices in everyday categories. But pressure has not been resulting in retrenchment, at least not to date. Spending remains positive, higher-income households continue to support aggregate demand, and lower-income consumers appear to be adjusting rather than retreating entirely.

For markets, the key question is not whether consumers feel good. It is whether spending, earnings, and investment hold up better than today’s low expectations imply. So far, they have.

1 Wall Street Journal. May 28, 2026. https://www.wsj.com/economy/q1-gross-domestic-product-revisione1a6ff93?mod=economy_lead_story

2 Fred Economic Data. May 28, 2026. https://fred.stlouisfed.org/series/CP

3 MSN. 2026. https://www.msn.com/en-us/money/savingandinvesting/us-companies-shamed-by-trump-tiptoe-into-a-tariff-refundrace/ar-AA23ThNr

4 Wall Street Journal. May 24, 2026. https://www.wsj.com/economy/teen-summer-jobs-f3ffdbfa?mod=economy_lead_pos4

DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable.

Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.

It is not possible to invest directly in an index. Investors pursuing a strategy similar to an index may experience higher or lower returns, which will be reduced by fees and expenses.

The ICE U.S. Dollar Index measures the value of the U.S. Dollar against a basket of currencies of the top six trading partners of the United States, as measured in 1973: the Euro zone, Japan, the United Kingdom, Canada, Sweden, and Switzerland. An investor cannot directly invest in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm that acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.

This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.

Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.

Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable. Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.

The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index. The Russell 1000 Growth Index is a well-known, unmanaged index of the prices of 1000 large-company growth common stocks selected by Russell.

The Russell 1000 Growth Index assumes reinvestment of dividends but does not reflect advisory fees. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

Nasdaq Composite Index is the market capitalization-weighted index of over 3,300 common equities listed on the Nasdaq stock exchange. The types of securities in the index include American depositary receipts, common stocks, real estate investment trusts (REITs) and tracking stocks, as well as limited partnership interests. The index includes all Nasdaq-listed stocks that are not derivatives, preferred shares, funds, exchange-traded funds (ETFs) or debenture securities. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

The Dow Jones Industrial Average measures the daily stock market movements of 30 U.S. publicly-traded companies listed on the NASDAQ or the New York Stock Exchange (NYSE). The 30 publicly-owned companies are considered leaders in the United States economy. An investor cannot directly invest in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

The Bloomberg Global Aggregate Index is a flagship measure of global investment grade debt from twenty-four local currency markets. This multi-currency benchmark includes treasury, government-related, corporate and securitized fixed-rate bonds from both developed and emerging markets issuers. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

The ICE Exchange-Listed Fixed & Adjustable Rate Preferred Securities Index is a modified market capitalization weighted index composed of preferred stock and securities that are functionally equivalent to preferred stock including, but not limited to, depositary preferred securities, perpetual subordinated debt and certain securities issued by banks and other financial institutions that are eligible for capital treatment with respect to such instruments akin to that received for issuance of straight preferred stock. An investor cannot invest directly in an index. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor.

The CBOE Volatility Index (VIX) is a calculation designed to produce a measure of constant, 30-day expected volatility of the U.S. stock market, derived from real-time, mid-quote prices of S&P 500 Index call and put options. On a global basis, it is one of the most recognized measures of volatility — widely reported by financial media and closely followed by a variety of market participants as a daily market indicator. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index. The NASDAQ-100 Index includes 100 of the largest domestic and international non-financial companies listed on The NASDAQ Stock Market based on market capitalization. The Index reflects companies across major industry groups including computer hardware and software, telecommunications, retail/wholesale trade and biotechnology. Index composition is reviewed on an annual basis in December. An investor cannot invest directly in an index.